From Reforms To Credit Alerts: How Oloworaran Is Transforming Nigeria’s Pension Industry
By Sunday Etuka

For decades, retirement in Nigeria carried a particular dread. A public servant who gave thirty-five years to the nation could finish a career and then begin a second, quieter career of waiting.
There were verification queues, delayed gratuities and monthly pensions that barely moved while prices climbed. In Abuja this month, the Director General of the National Pension Commission (PenCom), Ms. Omolola Oloworaran, announced that this era is ending.
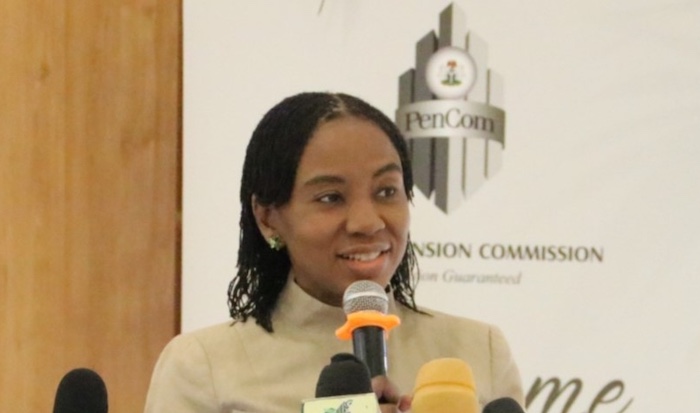
Speaking at the 2026 PenCom Conference for journalists on Tuesday, the PenCom DG said the pension system is delivering seven historic reforms in just over two years, with two more due within weeks. Her theme, “Reform to Reality,” was meant to signal that policy promises are now showing up as credit alerts in retirees’ accounts.
HISTORICAL PERSPECTIVE
Before 2004, most public sector workers belonged to a defined benefit arrangement funded on a pay as you go basis. The government paid pensions directly from current budgets, and workers did not build individual savings.
When budgets were tight or administration was weak, retirees paid the price. Arrears piled up, records were poorly kept and the obligations passed from one administration to the next.
The Pension Reform Act of 2004 changed the design. It created the Contributory Pension Scheme (CPS), in which each worker holds a Retirement Savings Account, and employers and employees contribute during working life. Licensed Pension Fund Administrators (PFAs) manage the money, Pension Fund Custodians hold the assets, and PenCom regulates the whole industry.
A later law, the Pension Reform Act of 2014, strengthened the framework and raised contribution requirements. It also contained a provision for a minimum pension guarantee, a floor beneath which eligible retirees would not fall. That guarantee has sat in the law for over a decade without taking effect.
The old and new systems have lived side by side. Workers who were already in service under the old arrangement, and those near retirement when reforms began, remained on defined benefit terms, creating legacy liabilities that governments struggled to clear.
The result is a pension landscape with two classes of retirees, those on the contributory scheme and those whose pensions are paid by the government, each with its own grievances.
HOW PENCOM IS BRIDGING THE GAP
Oloworaran organised her address around a series of firsts, each presented as evidence that the gap between promise and delivery is closing.
The first is Pension Boost 1.0, which she described as the first across the board increase for retirees under the CPS. According to the commission, monthly pensions for more than 241,000 retirees rose from N12.15 billion to N14.83 billion, with some low-level retirees seeing increases of up to 100 percent.
She described a typical retired civil servant who saw her pension rise by 61 percent after two credit alerts, and said some retirees saw their pensions double.
The second concerns retirees of the Nigeria Social Insurance Trust Fund (NSITF), whose pensions had not been reviewed in 21 years. The Director General said the commission invoked the law and directed a review, producing a 1,173 percent increase.
Combined monthly pensions for 2,168 retirees rose from N12.56 million to N159.95 million, and arrears of N8.7 billion were paid in full. She cited one retiree who moved from N18,000 a month to N206,000.
The third is the clearing of inherited liabilities. After President Bola Tinubu approved an N758 billion intervention, the Federal Government settled pension obligations, some outstanding since 2007, with payments reaching 957,000 beneficiaries.
The fourth involves accrued pension rights. Through a verification and enrolment exercise, accrued rights have been credited to the retirement savings of enrolled federal employees due to retire up to December 2029.
Oloworaran urged every eligible employee and every ministry, department and agency to finish enrolment before the exercise closes in December 2026.
She also announced a zero-waiting time policy, under which federal retirees begin receiving pensions as soon as they leave service, ending the return to the queue.
The fifth is speed. Retirement benefits that once took up to 21 months to approve are now approved in 48 hours. She described this as a mandatory service standard binding on every PFA, not a target.
The sixth is a new exit benefits scheme, in force since 1 January 2026. Eligible employees of Treasury funded agencies with at least ten years of qualifying service receive an additional benefit equal to 100 percent of their total annual emolument on top of their normal pension. The first 175 retirees received about N1.1 billion in August.
The seventh is a national distribution framework for the informal sector. Accredited pension agents are taking personal pension plans to markets, workshops, motor parks and farms, aiming to reach traders, artisans, farmers and transport workers who have long been outside formal retirement savings.
The commission presents this as both a coverage measure and a job creation measure, since every accredited agent is a new livelihood.
The two upcoming deliverables will be launched during National Pension Week, which runs from 26 to 30 October 2026.
The first is PenCare, a retiree health programme that will give eligible low-income retirees essential healthcare at no cost to them. It begins with 30,000 retirees, and the commission intends to extend it to all low-income retirees by next year.
The second is the minimum pension guarantee, which will set a floor below which no eligible CPS retiree will fall. For retirees with the smallest savings, the Director General said, that floor is the difference between survival and dignity.
PENSION ASSETS GROWTH
The reforms rest on a financial base that has expanded quickly. According to PenCom, pension assets rose from N20.7 trillion in July 2024 to N31.48 trillion in June 2026, an increase of more than N10.7 trillion in under two years.
In the same period, 938,229 Nigerians joined the scheme. Oloworaran noted she was working from June figures, suggesting more recent data may show further movement. That pool is increasingly being pointed at the domestic economy. She said pension funds are diversifying into real assets and local investments.
The Pension Industry Leadership Council has endorsed a first joint infrastructure investment vehicle of $250 million, with $200 million from pension fund operators serving as an anchor for investors through cash flows over ten years.
A further $15 million is expected from a government financial institution, with talks ongoing. She called it a beginning, adding that the commitment will grow as sound opportunities emerge, and promised rigorous project selection and uncompromising protection of contributors’ interests.
For a country with large infrastructure needs, long term pension capital is an obvious prize. It is also a responsibility, because the money belongs to workers who will depend on it in old age, and the history of public investment offers reasons for caution.
One persistent weakness in any contributory system is the employer who deducts pension from a worker’s pay and fails to remit it. Oloworaran said such conduct is a breach of trust and of the law.
Recoveries from defaulting employers set a record last year, she said, and this year has already passed it, with cumulative recoveries at N36.6 billion as of July 2026.
She promised the commission would find defaulters, recover the money and hold those responsible to account.
On the institutional side, the Pension Industry Leadership Council approved an independent assessment of the industry’s maturity against international standards on 24 September.
PenCom is also developing the Pension Transformation Agenda 2030, intended to set priorities and measurable milestones so the commission can be judged against its own targets.
Last week in Lagos, it unveiled the first edition of Pension Protocols, a record of the reforms and decisions shaping the industry.
COMMENDABLE GOVERNMENT INTERVENTION
The Director General was warm in her praise of the president. She said he settled obligations he did not create, approved new benefits where none existed and gave retirees certainty in place of delay. She added that she has come to believe he is the most supportive president of workers and retirees in the nation’s history.
That is a strong claim, and as with any official assessment of a government’s record, readers will weigh it for themselves. Retirees’ own experience, the pace of the promised rollouts and independent verification of the figures will matter more than any conference speech.
Oloworaran herself acknowledged that many households still face real pressures, and she said coverage must widen, compliance must deepen and benefits must grow. Her own words were plain: “The work is not finished.”
THE ROLE OF THE MEDIA
The conference itself was designed with accountability in mind. Dr Nana Musa, president of the Pension Correspondents Association of Nigeria, was represented by the association’s Treasurer, Oluwakemi Kindness.
She told colleagues that pension reporters must go beyond reporting announcements, explain policies clearly, ask relevant questions and keep public attention on issues affecting contributors and retirees. She pledged the association’s commitment to responsible pension journalism.
Sa’adu Jijji, Managing Director and Chief Executive Officer of Access ARM Pensions, speaking for the PFAs, thanked the Director General for the strategic reforms and pledged operators’ commitment to full implementation of the commission’s initiatives.
Oloworaran invited the press to hold her institution to account, to ask whether contributions are remitted and whether benefits are paid, and to bring the voice of the retiree into the conversation.
She also urged young Nigerians to start early by knowing their PFA, reading their statements and asking where their contributions are invested, and called on state governments and private employers to follow the federal example by paying fully and widening coverage.
THE WAY FORWARD
Several tests lie ahead. Will PenCare reach its first 30,000 retirees on schedule, and can it scale to all low-income retirees next year? How will the minimum pension guarantee be funded and who will qualify? Will the enrolment exercise finish before the December 2026 deadline? And will the infrastructure fund deliver secure returns without exposing contributors to avoidable risk?
For the retired civil servant at the heart of the Director General’s opening story, the questions are simpler. She wants the alert to arrive every month, on time, and large enough to matter.
Two decades after the contributory scheme was born, that remains the standard by which Nigeria’s pension reforms will ultimately be judged.