IMF, World Bank Hail Nigeria As Oyedele Demands Affordable Financing For Developing Nations
By Sunday Etuka

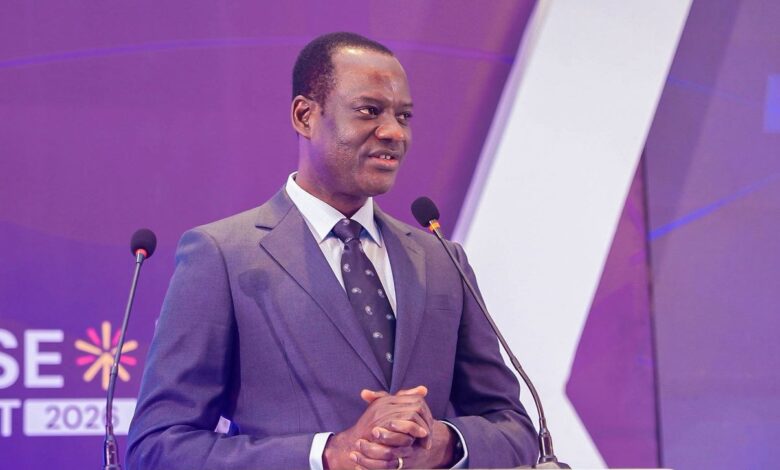
IMF Managing Director, Kristalina Georgieva, and World Bank Senior Managing Director, Axel van Trotsenburg, have commended Nigeria Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, for his chairmanship of G24 Board of Governors meeting.
The meeting was held on the sidelines of the IMF and World Bank Annual Meetings in Bangkok, according to a statement made available on Wednesday by the Head of Media, Ministry of Finance, Efe Ovuakporie.
Oyedele, who chaired the meeting, led calls for reform of global financial architecture to deliver more affordable financing, fairer representation and faster sovereign debt resolution for developing economies.
He said rising interest rates, widening fiscal deficits in advanced economies and growing financing demand for artificial intelligence and energy infrastructure had made borrowing more expensive for developing countries.
He called for progress on the IMF quota and governance reform, stronger representation for developing countries at the World Bank, improved access to development finance and more predictable, coordinated debt restructuring involving all creditors.
He also urged expanded climate financing, stronger international tax cooperation against avoidance and illicit flows and greater voice for developing countries in global decision making including G20.
In closing remarks, Oyedele said resilience must be built before a crisis through proactive policy preparation, artificial intelligence must be adopted and regulated responsibly to support inclusive job rich growth and international cooperation remains essential to managing shared risks such as energy insecurity, food price volatility, supply chain disruption, debt vulnerability and climate change.
Georgieva described the global economy as resilient with growth projected at about 3.1 percent through 2026 but cautioned that figure masked widening gap between economies benefiting from digital transformation, AI investment and critical mineral supply chains and those constrained by high energy costs, conflict or limited access to technology.
She warned persistent energy and food price pressures were keeping interest rates and debt servicing costs elevated and urged governments to rebuild fiscal buffers, preserve central bank independence, invest in digital infrastructure and skills and push for faster debt treatment under G20 Common Framework alongside further IMF quota reform.
Van Trotsenburg who represented World Bank President Ajay Banga reported that the Bank had mobilised about $27.4 billion in crisis related financing with ten countries activating dedicated crisis response instruments and nineteen others redirecting existing resources to urgent needs.
He flagged El Nino related risks to food security and grain prices and said the Bank remained focused on electricity access, healthcare, digital connectivity and job creation alongside mobilising private capital and climate finance.
Member interventions reinforced the reform agenda with Brazil, China and Pakistan backing stronger Global South representation and Bretton Woods reform, Philippines calling for deeper regional financial integration, Kenya urging building policy buffers and expanding local currency financing, Egypt citing supply chain disruption and capital outflows and Lebanon and Syria raising financing challenges facing conflict affected economies.
Incoming G24 Chair Pakistan pledged to keep development at the centre of agenda.
The meeting concluded that domestic reform alone will not shield developing economies from external shocks and that affordable finance, effective debt resolution, fairer representation in international institutions and sustained cooperation are equally necessary.