
The Central Bank of Nigeria (CBN) has cautioned that the N4.65 trillion raised in the banking sector recapitalisation exercise should not be mistaken for the end of reform, stressing that lasting financial stability depends on how well banks manage risks, not merely on how much capital they hold.
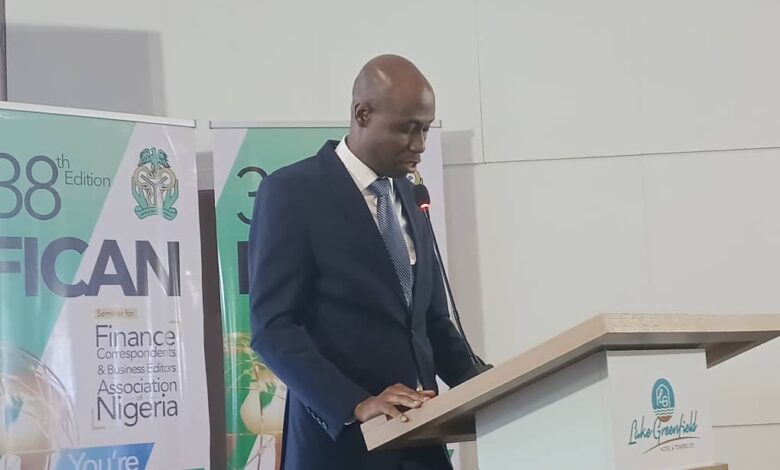
Director of Banking Supervision at the CBN, Dr. Olubukola Akinwunmi, made the point on Tuesday in a paper presented at the 38th Seminar for the Finance Correspondents’ Association of Nigeria (FICAN), titled Towards a Robust and Resilient Banking System: Sustaining Financial Stability in the Post-Recapitalisation Era.
According to Akinwunmi, the programme, announced by the CBN on 28 March 2024 and implemented between 1 April 2024 and 31 March 2026, mobilised about N4.65 trillion in fresh capital.
Domestic sources supplied 72.6 per cent, while international investors provided 27.4 per cent. As a result, 33 licensed banks met the revised minimum capital requirements, which he said reflects strong investor confidence in the sector.
He said the exercise was completed without disruption to financial intermediation, depositor confidence or payment system stability.
He noted, however, that the true measure of success will be whether banks can withstand future economic shocks, maintain public confidence and sustain lending to productive sectors, rather than the amount of capital raised.
The director described capital adequacy as a necessary condition for resilience but not a sufficient one, adding that a well-capitalised bank can still face trouble from poor governance, weak risk management, deteriorating asset quality, liquidity pressures, cyber threats or excessive risk taking.
To illustrate the point, he compared recapitalisation to the foundation of a building, saying a strong foundation alone does not guarantee the safety or durability of the structure.
Akinwunmi said the CBN is gradually withdrawing forbearance measures introduced during periods of severe stress, including the COVID-19 pandemic, foreign exchange pressures and high inflation.
He said the relief helped prevent a sharp deterioration in bank balance sheets and sustained credit flows, but was always meant to be temporary.
According to him, prolonged reliance on relief can obscure the true condition of banks, delay recognition of impaired assets and weaken market discipline.
He stressed that the aim is not to penalise banks but to restore normal prudential standards, with banks expected to recognise problem loans promptly and maintain adequate capital buffers.
He said stress testing, Basel III implementation and the Internal Capital Adequacy Assessment Process (ICAAP) are moving supervision from a compliance-based approach to a risk based one.
Banks are now required to conduct regular stress tests covering scenarios such as high inflation, exchange rate depreciation, recession, rising interest rates, higher loan defaults and cyberattacks.
Likening stress testing to a fire drill, he said it does not predict a crisis but helps banks and regulators identify vulnerabilities early.
The CBN issued its Guidelines on Risk Based Capital Requirement in March 2026, pursuant to Sections 13 and 63 of the Banks and Other Financial Institutions Act (BOFIA) 2020.
Under the framework, banks with higher risk, such as significant concentration, foreign exchange exposure, governance weaknesses or complex activities, are expected to hold more capital.
Banks must stress test all on and off-balance sheet credit exposures, including insider related facilities, over a twelve-month horizon. Those with capital shortfalls must report outcomes every six months, while others are assessed annually.
Akinwunmi said the framework ensures banks hold not just more capital, but the right amount for the risks they assume.
He said the CBN has strengthened its Regulation on Large Exposures and its Guidelines on Management of Credit Concentration Risk to limit excessive dependence on single borrowers, connected counterparties, sectors or economic activities.
“Banks must set internal exposure limits, conduct periodic stress tests and factor concentration risk into their ICAAP,” he said.
Hee added that diversification also supports development by directing credit to agriculture, manufacturing, infrastructure, technology, renewable energy and small and medium sized enterprises.
On governance, Akinwunmi said bank failures are often preceded by governance weaknesses rather than capital deficiencies alone.
The current framework rests on the Corporate Governance Guidelines for Commercial, Merchant, Non-Interest and Payment Service Banks and Financial Holding Companies in Nigeria, 2023, effective 1 August 2023.
Comparing capital to fuel and governance to the driver, he said a vehicle with abundant fuel, but poor driving remains vulnerable to accidents.
He described governance as the mechanism through which capital strength is converted into lasting resilience.
Akinwunmi told journalists that banking information is technical and a single figure can mislead without context.
He said a rising nonperforming loan ratio may reflect deterioration, earlier recognition or a change in the denominator, while a regulatory intervention may signal distress or show that supervision is working early as intended.
He said accurate, timely and well contextualised reporting helps the public tell genuine vulnerability from routine regulatory action, adding that the responsibility is shared: the media must verify before publishing, and the regulator must communicate clearly.
According to him, the post recapitalisation agenda focuses on stronger corporate governance, risk management, stress testing, operational resilience, disciplined credit allocation and supervisory effectiveness.
To support it, the CBN has intensified risk-based supervision, advanced Basel III implementation, introduced the Risk Based Capital Requirement Framework, strengthened governance standards, expanded stress testing programmes and continued the Rulebook Project to harmonise prudential requirements across the industry.