
Nigeria’s ambition to build a $1 trillion economy will ultimately be tested not by the elegance of its policy but by the number of factories it can attract, the volume of goods it can produce, the exports it can generate, and the billions of dollars of capital it can persuade investors to commit for decades.
That is why the unfolding battle over Nigeria’s free-zone regime deserves considerably more attention than it has received.
At stake is not merely a disagreement over tax administration. It is a fundamental question about what Nigeria’s free zones are meant to be, genuine investment enclaves with internationally competitive incentives, or conventional business locations that bear the name “free zone” while gradually losing the fiscal and regulatory advantages that initially attracted investors there.
The draft Nigeria Export Processing Zones (Domestic Sales, Fiscal Alignment and Customs Treatment) Regulations, 2026, obtained for this report, provides a revealing window into the proposed new architecture.
The document is issued under the Nigeria Export Processing Zones Act and the Nigeria Tax Act 2025. It says its objectives include improving investor confidence, protecting government revenue and enhancing the global competitiveness of the zones.
NEPZA’s published investment information says approved enterprises in the zones enjoy exemptions from legislative provisions relating to taxes, levies, duties and foreign-exchange regulations, alongside capital-repatriation provisions and other incentives.
The draft regulations state that, subject to the new treatment of domestic sales, enterprises operating within the zones remain exempt from taxes, rates, levies, fees and fines imposed by federal, state and local authorities, including indirect taxes, stamp duties and VAT, in accordance with the NEPZA Act and the applicable tax framework.
The draft proposes that an enterprise qualify for tax exemption on profits only where at least 75 per cent of annual turnover comes from exports and no more than 25 per cent from sales into Nigeria’s customs territory.
It further provides that, from January 1, 2028, profits arising from sales into the Nigerian Customs Territory will be fully subject to tax, irrespective of the percentage of domestic sales.
That is a major policy change: And major policy changes require major consultation. This is so because some investors might have staked their investments outside this sudden change, and they will consider this a policy somersault. The inconsistency in policy formulation, rather than encouraging investment inflow, further drives it miles away.
The question the government must answer: Nobody seriously arguing for industrial development should defend the abuse of tax incentives.
A free-zone company that illegally diverts duty-free goods into the domestic market should face sanctions. The draft itself is unequivocal on this point.
Unauthorised movement of duty-free goods can trigger customs duties, import VAT and other charges, customs offences, breach of zone licence conditions, administrative penalties, seizure and possible prosecution. That is not controversial.
The real issue is whether the government should address abuse by strengthening enforcement while preserving the investment proposition, rather than allowing fiscal reform to gradually erode the very incentives that distinguish a free zone from the rest of the economy.
There is a workable middle ground: Keep the incentives; Make them conditional; Measure the economic returns; Punish abuse; Withdraw benefits from non-performing enterprises, but protect investors who have complied with the law and made long-term investments based on legally established incentives.
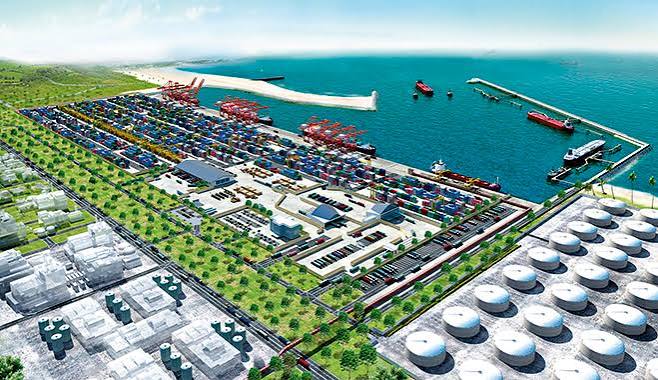
The Dangote lesson: The most powerful argument for maintaining credible free-zone incentives comes from what Nigeria itself has already demonstrated. The Dangote Refinery and Petrochemical complex is located within the Dangote Industries Free Zone, Lekki, Lagos, and was actually midwifed by NEPZA but recently transferred to the Oil and Gas Free Zone Authority (OGFZA), an action that has yet to be fully explained. Nevertheless, the economic lesson is directly relevant to how a free zone can positively impact the economy.
The lesson is therefore that Nigeria’s free-zone model can be a powerful instrument for attracting and anchoring investments of a scale that might otherwise be extremely difficult to establish under the ordinary domestic regulatory and fiscal environment.
Remove the economic advantages from the model, and the government must answer a simple investment question: Why would the next Dangote-scale investor choose the free zone?
That question becomes even more important when competing jurisdictions offer investors specialised regulatory regimes, tax incentives, customs advantages and integrated infrastructure.
A warning from investors’ time horizons: Investment does not operate on the political calendar. A minister may serve for several years. A government may change.
But a refinery, petrochemical plant, automobile factory, pharmaceutical facility, or export-processing plant may require 10, 15, 20, or even 25 years to recover capital and generate expected returns. That is precisely why policy consistency matters.
That should be a warning to policymakers. A government can change a tax rule overnight. An investor cannot relocate a billion-dollar factory overnight.
NEPZA’s place in the architecture: Perhaps the most significant revelation in the draft regulations is that they actually acknowledge NEPZA’s continuing regulatory jurisdiction.
Regulation 29 provides that NEPZA “shall remain the exclusive regulator” for licensing, operational oversight, supervision and non-tax administration within the zones.
The draft separately gives the Nigeria Revenue Service (NRS) exclusive responsibility for tax administration and the Nigeria Customs Service exclusive responsibility for customs control and enforcement.
That division of responsibilities is logical. NEPZA should regulate the zone. The revenue authority should collect taxes. Customs should control customs. The danger lies not in specialisation, but in fragmentation without coordination.
That is why NEPZA must remain the institutional centre of operational regulation. The draft itself recognises NEPZA’s role. There appears to be some intriguing contradictions at the heart of the debate.
According to the office of the Minister of Industry, Trade and Investment, under whose purview the document was drafted, NEPZA, Customs and the NRS have been given equal powers to jointly issue implementation guidelines covering domestic-sale thresholds, customs clearance, tax filing, audits, record-keeping, inspections and digital systems.
The sensible policy conclusion, therefore, should be to strengthen NEPZA’s capacity to perform that role rather than diminish its authority or create competing regulatory centres.
The workers’ protest cannot simply be dismissed.
At this point, the position of the union members deserves to be taken seriously. Workers who carried placards against the proposed changes were not merely protesting a technical tax regulation.
Their concern hinges on the fact that those decisions, if not well crafted along globally acceptable free zone rules, would have a negative impact on their daily FDI drive, employment environment, and welfare.
There is, however, a legitimate transparency question: What specific inputs did NEPZA make during the policy process, which of those inputs were accepted, which were rejected, and why?
That question becomes especially important if unions or other stakeholders maintain that key decisions were reached without adequate consultation.
It is worthy of note that, the draft says enterprises enjoying incentives validly granted before commencement of the Act may continue to enjoy them only for the unexpired portion of their statutory approval period and according to the applicable law and original approval.
It also says that incentives cannot be extended beyond their statutory sunset period except through the legally authorised process.
This is where the government needs to tread carefully. An investor who entered Nigeria under one set of rules is not the same as an investor arriving tomorrow. The first has already committed capital based on a government-created investment proposition.
Policy reform should therefore distinguish between: New incentives, existing incentives, and incentives already embedded in legally approved investment commitments. That distinction can protect the government’s revenue interests without undermining investor confidence. Do not kill the goose while trying to count the eggs.
Nigeria needs to ask what produces greater economic value: collecting more tax from a smaller industrial base, or maintaining a competitive investment environment capable of producing more factories, more jobs, more exports and ultimately a larger taxable economy.
The answer should be found through evidence rather than ideology. The government should publish a comprehensive cost-benefit assessment of the free-zone incentive regime.
Why NEPZA should have stronger presidential coordination: There is also a broader institutional lesson. Free zones cut across taxation, customs, ports, immigration, infrastructure, trade, investment promotion, manufacturing and foreign exchange.
Keeping NEPZA within a single ministry can expose a long-term national economic programme to the policy priorities of successive ministers. A stronger presidential coordination mechanism would not necessarily mean abolishing ministerial oversight.
It could mean creating a Presidential Special Economic Zones Council bringing together NEPZA, OGFZA, the Ministry of Finance, Industry, Trade and Investment, Nigeria Revenue Service, Customs, the Central Bank, ports authorities, infrastructure agencies and private-sector representatives.
Such a body could establish a single national free-zone strategy and prevent one agency from pursuing revenue objectives while another pursues investment objectives without sufficient coordination. That is how Nigeria can begin to emulate successful economic-zone jurisdictions.
The Ministry’s publicly reported position is that the reforms are intended to improve fiscal accountability while preserving the competitiveness of free zones. Oduwole has also said the reform process involved NEPZA and OGFZA and that the agencies would retain licensing and operational responsibilities.
The question is whether there is an underlying motive: In hindsight, this union once strongly moved against actions taken by the former Minister of Industry, Trade and Investment, Dr. Okechukwu Enelamah, accusing him of attempting to privatize the agency’s assets through a shadow firm illegally.
Diversion of Public Funds: The union raised the alarm over the withdrawal of N14.38 billion from NEPZA’s capital project budget account. The funds were transferred to a private entity named the Nigerian Special Economic Zones Company (NSEZCO)—which the union exposed through investigations to be registered as Nigeria Sez Investment Company Limited.
Government & Legislative Backing: The union’s pushback gained heavy legislative momentum when the Nigerian Senate and the House of Representatives Committee on Commerce stepped in. The National Assembly faulted the transfer, officially labelling it irregular because a private company with 75% private ownership was receiving 100% of its funding directly from the federal budget without private equity matches. The Senate subsequently ordered Enelamah to return the N14.3 billion to the national treasury.
Truth be told, NEPZA has witnessed some overbearing policy from the ministry, and its union has therefore received this current one with skepticism. If evidence shows that this will reduce investment, weaken confidence or make the country less competitive against rival free-zone jurisdictions, then the president should wade in without delay.
The presidency should look beyond the tax ledger: President Bola Ahmed Tinubu’s $1 trillion economic ambition requires Nigeria to think in terms of productive capacity. The underlisted are some of the best sources of productive capacity that the country should optimise.
Factories, Exports, Oil & Gas (Petrochemical), Industrial parks, Special Economic Zones
Investors are sure to gravitate more toward these production lines if the rules under which they enter will remain sufficiently predictable to justify long-term capital commitments.
For example, the Dangote experience provides an instructive example of what can happen when a large industrial project is embedded within a free-zone ecosystem offering infrastructure, customs advantages, tax incentives and regulatory coordination.
Investment incentives are not an end in themselves. They are a means of attracting productive capital. Therefore, the Presidential authorisation for 100 percent export to the customs territory by free zone operators should be allowed pending the amendment of the entire NEPZA Act.
The choice before Nigeria: The Federal Government has every right to demand accountability from free-zone operators. It has every right to stop diversion. It has every right to ensure that companies benefiting from incentives actually produce exports, jobs and investment. It has every right to collect duties legitimately due to domestic transactions. But those objectives can coexist with a stronger NEPZA.
They can coexist with incentives.
They can coexist with rigorous audits.
They can coexist with customs enforcement.
They can coexist with a modern revenue authority.
The Final Test: The Federal Government should pause long enough to ask one question before making fundamental changes to the free-zone regime:
Will the investor be considering a $500 million, $1 billion, or $5 billion project and regard Nigeria’s free zones as more attractive and predictable after these reforms than before them?
If the answer is yes, proceed. If the answer is uncertain, consult more widely. If the answer is no, reform the reform.
The country’s ambition to become a $1 trillion economy requires more than policy declarations. It requires industrial plants, ports, factories, jobs, exports and investors prepared to put billions of dollars behind long-term bets on Nigeria.
The country needs a free-zone system that is tough on abuse but generous toward productive investment; strict on compliance but predictable in its incentives; coordinated across government but clear about who regulates what. And above all, it needs a regulator with the institutional strength to protect the integrity of that system.
NEPZA should not be weakened because the free-zone regime needs reform. It should be strengthened precisely because the regime needs reform. That is the difference between dismantling a system and fixing it.
And if Nigeria’s free zones are genuinely expected to become engines of industrialisation and contributors to President Tinubu’s $1 trillion economic ambition, that distinction may prove decisive.
Rather than strip NEPZA of regulation, the government should make NEPZA’s statutory regulatory roles unambiguous and institutionally secure, while separating tax collection and customs enforcement from zone regulation.
Conclusion: The actual concerns of the operators is that the Federal Government must understand that most parts of the NEPZA Act 63 of 1992 are obsolete and constrain foreign direct investment by making the free zones look legally outdated, commercially uncertain, and structurally inflexible.
While the law may have been adequate when the scheme was smaller and the market less complex, it is no longer appropriate for a modern, globally scaled marketplace that depends on large, long-term capital commitments, technology partnerships, and investor confidence.
In practical terms, the age and limitations of the law now undermine growth by restricting the Authority’s ability to attract the kind of investment required for expansion, innovation, and competitiveness.
One major limitation is regulatory uncertainty. Foreign investors typically look for clear, modern, and predictable legal frameworks before committing capital. Where an entity continues to operate under outdated law, investors may be concerned that the law does not adequately address current realities such as digital trade, cross-border transactions, competition issues, governance standards, infrastructure financing, dispute resolution, or investor protections.
Even when the scheme is commercially viable, the perception of legal fragility can reduce investor appetite because capital prefers environments where rights, obligations, and enforcement mechanisms are clearly defined.
A second constraint is limited corporate and financing flexibility. Older laws often impose narrow rules on ownership structure, governance arrangements, borrowing powers, concessions, public-private partnerships, and asset development models. This can make it difficult to structure deals in ways that international investors are familiar with.
The outdated law may also weaken institutional credibility. Global investors assess not only the market opportunity but also the legal sophistication of the host institution.
Conversely, Oduwole must act now by promoting an Executive Bill before the Federal Executive Council to replace the existing NEPZA Act, which supports only export-oriented activity, with a more liberal, globally acceptable Special Economic Zones model that is intricately designed with progressive rules and regulations acceptable to modern marketplace operators.